Hiring a financial advisor is a little like buying a house.
Deciding to buy is the big moment. But nobody talks much about what comes after: the paperwork, the boxes, figuring out where everything goes.
Onboarding with an advisor works the same way. You've decided to get help. So what actually happens next?
If you live in Morgan Hill, Gilroy, Hollister, or anywhere else in the South Valley or greater South Bay and you're thinking about taking that step, here's a plain-English look at a typical financial advisor onboarding process. We'll cover what it usually involves, how long it can take, and which questions are worth asking along the way.
Let's break it down…
Step 1: Do your homework before the first meeting
Before you share a single account statement, it's reasonable to check out the person and the firm you're considering.
The SEC's free search tools on Investor.gov and the Investment Adviser Public Disclosure (IAPD) website show whether an adviser is currently registered. They also show background information such as the firm's business practices, fees, conflicts of interest, and any disciplinary history.1
That background comes from the firm's Form ADV. Part 2 of the form is the firm's "brochure," a plain-English document that covers its business practices, fees, conflicts of interest, and disciplinary information.2
Then there's Form CRS, a short relationship summary. Advisers and brokers are required to give you one when they start a relationship with you.3 It describes the services offered, the fees and costs you'll pay, the firm's conflicts of interest, and the standard of conduct it has to follow. When a firm acts as your investment adviser, it has to act in your best interest and not put its interests ahead of yours.4
Every firm's relationship summary uses similar headings in a similar order, which makes it easy to compare a few advisors side by side.5 You can find ours on our Client Relationship Summary page.
Step 2: The introductory conversation
Most onboarding processes start with a conversation, not a contract.
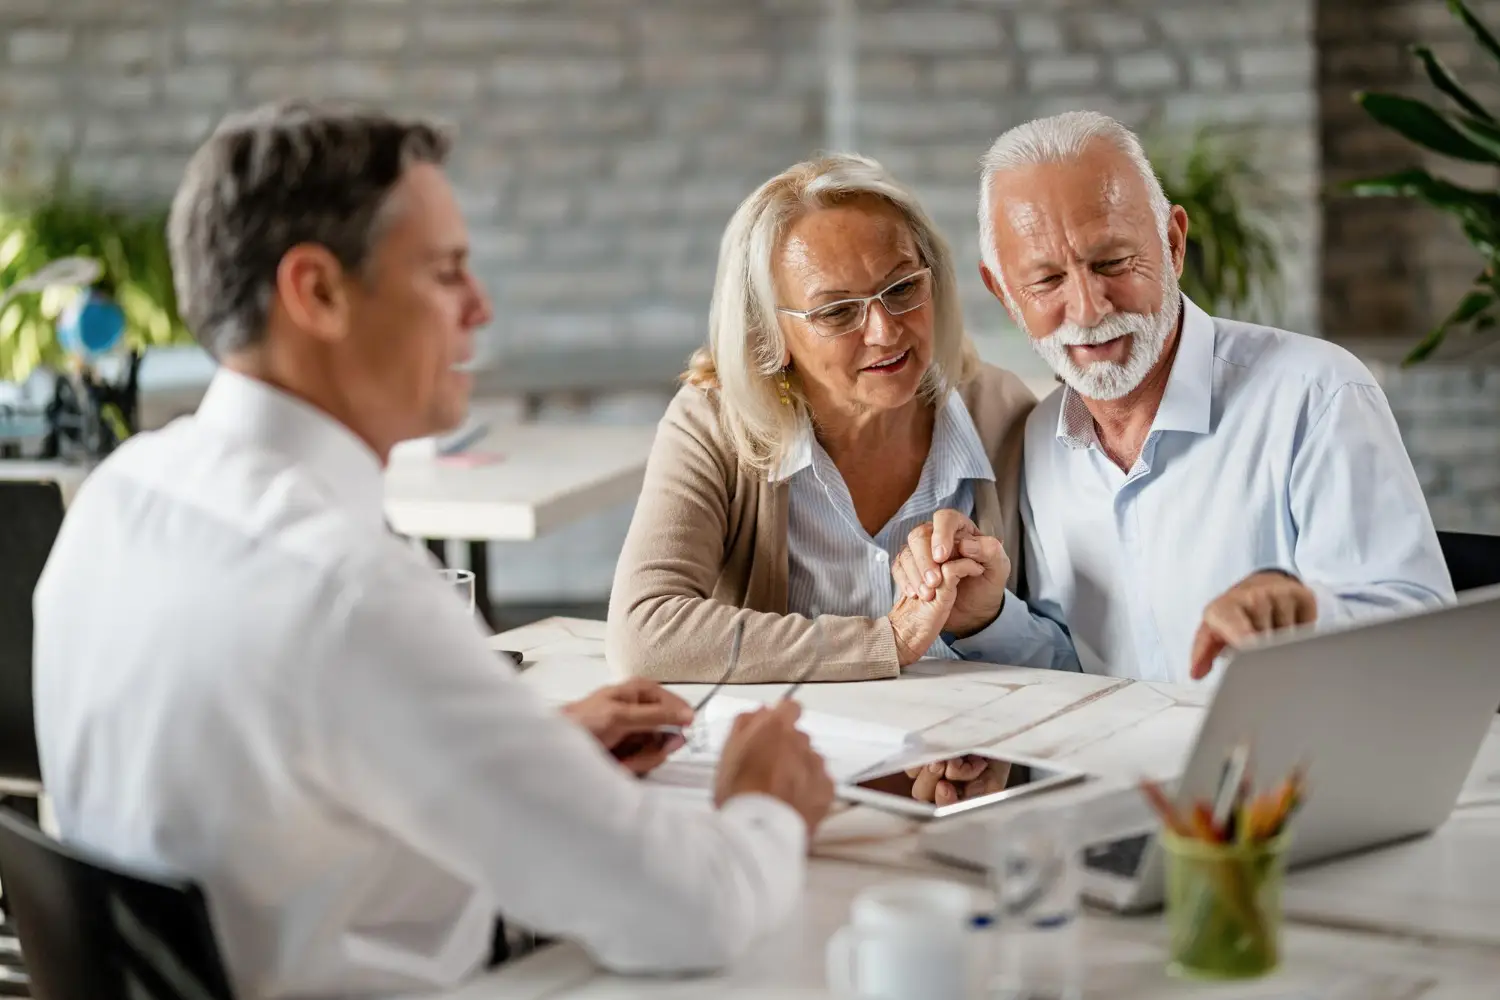
Think of it as a two-way interview. The advisor is learning about your goals, your concerns, and the big picture of your finances. You're learning how they work, how they're paid, and whether the relationship feels like a good fit.
A few questions worth asking:
- How are you paid, and what will I pay in total? Ask about advisory fees, fund expenses, and any other costs.
- What happens after the plan is built? Find out how often you'll meet and what ongoing service includes.
- Who will I work with day to day? At some firms that's the advisor you met. At others it's a broader team.
- Where will my money actually be held? This one matters more than most people realize. More on it below.
Step 3: Gathering your financial picture
If you decide to move forward, the discovery phase begins. This is where the advisor builds a complete picture of where you stand today.
It helps to start pulling these together:
- Recent statements for workplace retirement plans (401(k), 403(b)), IRAs, brokerage accounts, and bank accounts
- Your most recent federal and California tax returns
- Recent pay stubs and, for many Morgan Hill households, equity compensation details such as RSU vesting schedules or stock option grants
- Pension statements and your Social Security benefit estimates
- Insurance policies: life, disability, long-term care, home, and auto
- Estate documents: wills, trusts, powers of attorney, and your current beneficiary designations
- For Gilroy and Hollister families who run a business, farm, or ranch: business financial statements and any buy-sell or succession agreements
Don't worry if your records aren't perfectly organized. Helping you sort through them is part of the advisor's job.
Step 4: Keeping your information private
You're handing over account numbers, your Social Security number, and years of tax returns. Asking how that information will be protected is completely fair.
SEC-registered investment advisers are covered by Regulation S-P, the federal privacy rule for nonpublic personal information.6 It's the reason advisers give you a privacy notice explaining what they collect, how they share it, and how you can limit some of that sharing.
In 2024, the SEC strengthened Regulation S-P. Covered firms now need a written incident response program designed to detect, respond to, and recover from unauthorized access to customer information. If sensitive customer information is accessed without authorization, the firm generally must notify affected individuals as soon as practicable, and no later than 30 days after it becomes aware of the incident. Larger firms had to comply by December 3, 2025, and smaller firms by June 3, 2026.6
You can read how we handle client information on our Financial Advisor Confidentiality & Privacy page.
One practical tip: share sensitive documents through a secure portal or in person rather than by regular email, and ask your advisor which method they use.
Step 5: Opening and transferring accounts
Now back to that "where will my money be held?" question.
With limited exceptions, SEC-registered investment advisers are required to keep client funds and securities with a "qualified custodian," such as a bank or a registered broker-dealer.7 In other words, your advisor manages the investments, but a separate institution holds them.
The custodian generally sends account statements directly to you, at least quarterly. It's a good habit to compare those statements with any reports your advisor sends.7
Existing brokerage accounts are usually moved through the Automated Customer Account Transfer Service (ACATS). If there are no problems, an ACATS transfer should take about three to five business days from the time the new firm enters the request.8
Not everything moves that smoothly, though. Some holdings may not transfer at all, such as securities sold only by your old firm or mutual funds the new firm doesn't carry. Selling those may affect your taxes, and there may be transaction fees at either firm.8 Before anything moves, it's worth talking through what transfers as-is, what might be sold, and what the trade-offs are.
If you're still working, your current employer's 401(k) often stays put. Even then, it can still be built into your overall plan.
Step 6: The plan, and what comes after
Once the information is gathered, the advisor analyzes it and comes back with recommendations. Those typically cover how your accounts work together, where taxes might be managed more efficiently, any gaps in insurance or estate planning, and how income could be structured in retirement.
But onboarding isn't the finish line. A plan is a snapshot of one moment in time. Careers change, markets move, tax laws get rewritten, and families grow. The ongoing relationship is where the plan gets revisited and adjusted as those things happen.
How long does onboarding take?
It depends on how complex your situation is. A household with a couple of retirement accounts can move faster than one with equity compensation, a family business, rental property, and a trust.
For us, initial onboarding typically takes a few weeks, depending on complexity. You can see the steps on our Becoming a Client page.
The biggest variables are usually how quickly documents come together and how many accounts need to move.
The bottom line
A well-run onboarding process should leave you informed, not rushed. By the end of it, you should know how your advisor is paid, where your money is held, how your information is protected, and what happens next.
If you're in the South Valley and want to see how this works with us locally, visit Financial Advisor in Morgan Hill, CA, Financial Advisor in Gilroy, CA, or Financial Advisor in Hollister, CA. Or if you have questions about your own situation, let's talk.
Sources:
- Investor.gov (SEC), "How to Check Out Your Investment Professional"
- Investor.gov (SEC), "Investor Bulletin: Form ADV – Investment Adviser Brochure and Brochure Supplement"
- Investor.gov (SEC), Glossary: Form CRS
- Investor.gov (SEC), "Relationship Summaries (Form CRS or Form ADV Part 3): Investor Bulletin"
- Investor.gov (SEC), Investor.gov/CRS
- SEC, "Enhancements to Regulation S-P: A Small Entity Compliance Guide," 2024
- Investor.gov (SEC), "Investor Bulletin: Custody of Your Investment Assets"
- Investor.gov (SEC), "Investor Bulletin: Transferring Your Investment Account"
This article is for general educational purposes only. It was developed from sources believed to be accurate as of its publication date, and rules and figures can change. The information herein is not intended as individual investment, tax or legal advice. Please consult with your personal advisor, legal or tax professionals for specific information regarding your individual situation. See our Terms & Disclosures.